Nursing Home Deposits and Upfront Fees: Questions Before Paying
A nursing home may ask a family to sign financial paperwork before admission. That paperwork can include legitimate charges — but it can also contain language the family should question.
Federal rules do not ban every nursing-home deposit. They do prohibit Medicare- and Medicaid-certified facilities from requiring a third party to personally guarantee payment as a condition of admission, and they restrict extra payments demanded from Medicaid-eligible residents as a condition of admission or continued stay.
The exact answer depends on the resident’s payer, Medicaid status, facility certification, state law, and the wording of the agreement.
First identify who is paying
Before discussing a deposit, identify the expected payer:
- Original Medicare;
- Medicare Advantage;
- Medicaid;
- Medicaid pending;
- private pay;
- long-term-care insurance;
- VA benefits; or
- another source.
The rule for a private-pay resident can be different from the rule for someone already eligible for Medicaid.
A family member cannot be required to personally guarantee the bill
Federal nursing-home regulations at 42 CFR §483.15 prohibit a Medicare- or Medicaid-certified facility from requesting or requiring a third-party guarantee of payment as a condition of admission, expedited admission, or continued stay.
This means a facility should not make an adult child personally liable for the parent’s nursing-home bill simply to secure admission.
However, the regulation allows a representative who has legal access to the resident’s money to agree to use the resident’s own funds to pay the facility, without assuming personal financial liability.
Read the signature block carefully.
“Responsible party” language deserves a close look
An admission agreement may use terms such as:
- responsible party;
- financial agent;
- representative;
- sponsor;
- guarantor; or
- authorized representative.
The label alone does not tell you the legal effect.
Ask:
“Does this signature make me personally liable from my own money, or does it only require me to use the resident’s funds that I legally control?”
If the answer is unclear, do not sign until it is clarified.
Medicaid-eligible residents have additional protection
Federal rules state that a Medicaid-certified nursing facility may not charge, solicit, accept, or receive an extra gift, donation, money, or other consideration as a precondition of admission, expedited admission, or continued stay for a person eligible for Medicaid, beyond amounts permitted under the Medicaid state plan.
CMS guidance specifically warns against requiring a Medicaid resident or family to pay an additional private-pay amount or deposit as a condition of admission.
A facility also may not require a person to promise to remain private pay for a set period before applying for Medicaid.
Medicaid-pending is more complicated
A person whose Medicaid application is still pending is not necessarily treated the same as a person already determined eligible.
CMS guidance says a facility may charge an applicant or resident while Medicaid eligibility is pending, including through a deposit or payment arrangement, subject to state rules.
If Medicaid is later approved retroactively, state rules can affect refunds and adjustments.
Ask the facility:
- What will we pay while Medicaid is pending?
- Is the payment refundable if Medicaid is approved retroactively?
- What date of eligibility are you expecting?
- What state rule controls the refund?
- What happens if Medicaid denies the application?
Get the policy in writing.
Our guide Can a Nursing Home Admit Someone While Medicaid Is Pending? covers this situation in more detail.
Private-pay deposits can be permitted
Federal CMS guidance says the admission rule does not prohibit a facility from charging a deposit or requiring a promissory note from someone whose stay is not covered by Medicaid, subject to applicable law.
That means a private-pay deposit is not automatically illegal.
Still ask:
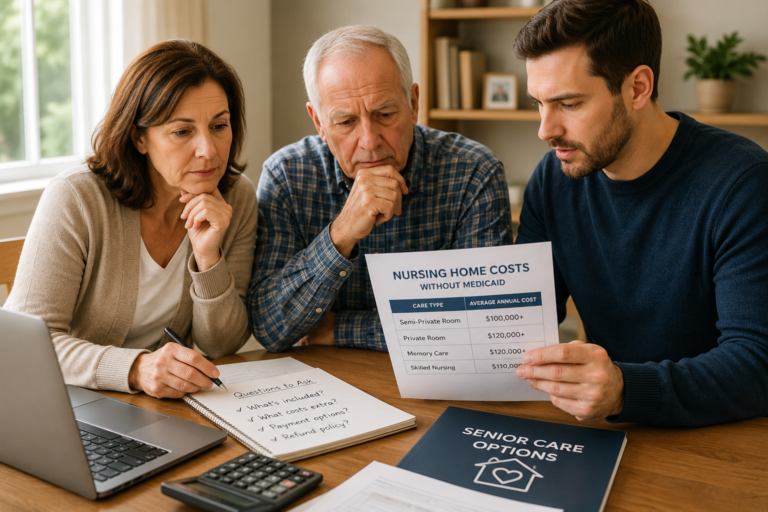
- How much is the deposit?
- What does it secure?
- Is it refundable?
- When is it applied to the bill?
- What deductions may be taken?
- What happens after death or discharge?
- What state law governs it?
Refundable resident funds require protections
CMS guidance explains that when a refundable deposit remains the resident’s money, federal resident-fund protections can apply, including surety-bond requirements.
The facility should be able to explain:
- where the deposit is held;
- whether interest accrues;
- when it becomes facility income;
- how it appears on the resident statement; and
- how it is refunded.
Do not hand over a large check without a written receipt and contract terms.
Medicare-covered rehab should not be confused with long-term private pay
If a resident enters a SNF for Medicare-covered rehabilitation, ask what charges are expected under Medicare and any secondary insurance.
A facility may legitimately collect estimated coinsurance or noncovered amounts in some circumstances, but the family should understand what the charge represents.
Ask for an itemized explanation.
If the resident has Medigap, verify whether the supplement covers Medicare SNF coinsurance before paying a large estimated balance.
Ask for the full rate sheet
Before admission, request written information showing:
- base daily or monthly rate;
- care-level charges;
- therapy charges;
- pharmacy arrangements;
- supplies;
- transportation;
- private room fees;
- beauty/barber services;
- television or phone charges;
- laundry;
- deposits;
- one-time fees;
- late fees; and
- rate-increase procedures.
A deposit is only one part of the financial agreement.
Do not sign blank financial forms
Every financial document should be complete before signature.
Do not sign:
- blank promissory notes;
- blank credit-card authorizations;
- forms with missing rates;
- documents that refer to attachments you were not given; or
- a personal-guarantee clause you do not understand.
Keep a complete signed copy.
Ask what happens if the payer changes
Many residents move from one payer to another.
Examples:
- Medicare rehab to private pay;
- Medicare rehab to Medicaid;
- private pay to Medicaid;
- insurance reimbursement to personal funds.
Ask the nursing home to explain in writing how:
- rates change;
- deposits are credited;
- outstanding balances are handled;
- Medicaid applications affect billing; and
- refunds are calculated.
A practical example
Suppose Sarah’s mother is entering a Medicare- and Medicaid-certified nursing home as private pay while a Medicaid application is pending.
The facility asks Sarah to sign as the “Responsible Party” and provide one month of private-pay charges upfront.
Sarah asks whether her signature makes her personally responsible.
The facility revises the explanation: Sarah is signing only as her mother’s financial agent, using her mother’s funds, not guaranteeing the bill with Sarah’s own money.
Sarah also asks what happens to the upfront amount if Medicaid is approved retroactively.
The facility provides its written Medicaid-pending refund policy.
Those two questions can prevent major disputes later.
Ten questions before paying an upfront amount
- What exactly is this fee or deposit called?
- Who legally owes it — the resident or me personally?
- Is the resident Medicaid-eligible, Medicaid-pending, Medicare-covered, or private pay?
- What federal or state rule allows the charge?
- Is the money refundable?
- Where is it held?
- When is it applied to the resident’s bill?
- What happens if Medicaid is approved retroactively?
- What happens after discharge or death?
- Can I have the complete agreement and rate sheet before paying?
If the facility will not explain the charge in writing, consider getting help from the state survey agency, Long-Term Care Ombudsman, Medicaid agency, or an elder-law attorney.
Sources and review date
Sources checked October 11, 2026. This article discusses federal rules for Medicare- and Medicaid-certified nursing facilities. State contract, deposit, Medicaid-pending, and resident-fund rules can add protections or requirements.